Whatever life stage you’re at, each year can bring a whole lot of change – new jobs, new babies, new homes! At each of these changes, you’ll need to make sure you have the right Singapore insurance for you. There are four important insurance options when it comes to coverage for expats, according to Pacific Prime Singapore. Take a look at the information below on home contents insurance, health, maternity and dental insurance in Singapore, and then take the steps you need to protect yourself from hefty bills or losses in the year ahead.
#1 Ensure that you’ve got the health insurance you need
Even if you’ve got health insurance through work, chances are that it’s not enough to sufficiently cover all your medical needs or those of your family. In fact, when it comes to employer-provided health insurance in Singapore, some of the most common coverage limitations include:
- Singapore-only coverage
- No outpatient benefits
- No dental and maternity benefits
- Limited network of doctors and specialists
- No preventative care benefits
- No wellness benefits
Many expats choose to buy private health insurance to supplement their work-provided plans. Buying top-up insurance can provide coverage where your current policy is lacking.
Top-up insurance in Singapore
For anyone who feels their existing health insurance benefits may not be enough coverage, top-up insurance is a tailored insurance solution that considers your existing insurance benefits and provides additional coverage where your plan’s benefits are lacking. As expats don’t have the same access to public healthcare options as Singaporeans do, top-up insurance is very useful. It’s also important to consider whether you want coverage outside of Singapore since most group insurance plans don’t offer it.
Consider international health insurance
If you plan to enjoy some regional holidays or are travelling for work, a comprehensive international health insurance plan that covers your medical costs in Singapore and around the world is another must-have.
Designed to cover policyholders on a worldwide basis, international health insurance for expats and frequent travellers is ideal. This type of health insurance option tends to feature higher coverage limits and a wider range of benefits in your country of residence, ensuring you have access to the highest quality healthcare possible.
While international health insurance is generally more costly than a local plan, the pros definitely outweigh the cons. They typically offer guaranteed lifetime renewability, as well as more options for pre-existing condition coverage – for example, via an additional premium or waiting period.
#2 Make sure any dental work is covered, too
Having a health insurance plan doesn’t necessarily mean that you have dental coverage. Whether you have an existing policy without dental benefits, or you have no plan and want to take care of your dental health without paying out of pocket, dental insurance in Singapore is highly advisable. Dental fees here are high, with treatment courses potentially costing tens of thousands of dollars.
If you already have an existing health insurance plan, you can add dental benefits to it. Or, you can work with a Singapore insurance broker like Pacific Prime Singapore to create an individual dental insurance plan with dental benefits to meet your individual needs.
#3 Plan ahead if you’re planning on starting a family
Planning on growing a family while living overseas? Maternity insurance is a must – having a baby in Singapore is expensive! Maternity insurance is designed to cover all expenses associated with prenatal care, such as doctor check-ups, ultrasounds and blood tests. It also covers all expenses related to giving birth – from normal delivery to medically necessary C-sections – such as the hospital stay, doctor’s fees and newborn care for up to the first 90 days of the baby’s life, along with vaccinations. Having a comprehensive maternity insurance plan in place is the best way to ensure that all of these costs are covered.
At the same time, it’s important to mention that standalone maternity insurance policies don’t exist. This means you’ll need to add maternity cover to a health insurance plan, giving you access to other benefits such as inpatient care and outpatient consultations.
You should also add maternity benefits to your insurance policy as early as possible since they come with a waiting period of anywhere from 10 to 24 months. This means you’ll have to wait until the specified time period is up before making a claim.
Typical postnatal care for both the mum and baby includes routine doctor’s visits for health check-ups and even some lab work. Newborn postnatal care also includes vaccinations, which can easily cost over $1,300 in a private clinic. Some insurance plans include coverage for help with breastfeeding by a lactation consultant or other professional.
#4 Make sure your valuables are protected with home insurance
Home insurance in Singapore is particularly beneficial for expats who are renting. Theft isn’t a major issue here, but this type of insurance also covers accidental damage and fire or flood damage. You can get coverage for everything from wedding rings and expensive watches to electronics and sports equipment, and that art piece you just couldn’t leave Thailand without!
You can also opt for a home insurance policy that insures your belongings on a worldwide basis, so you’re covered wherever you are in the world.
While home contents insurance in Singapore generally protects everything under your roof, fire insurance protects the actual roof itself. So, you’ll want to consider fire insurance, too. Having both types of policies can ensure full coverage and offer peace of mind.
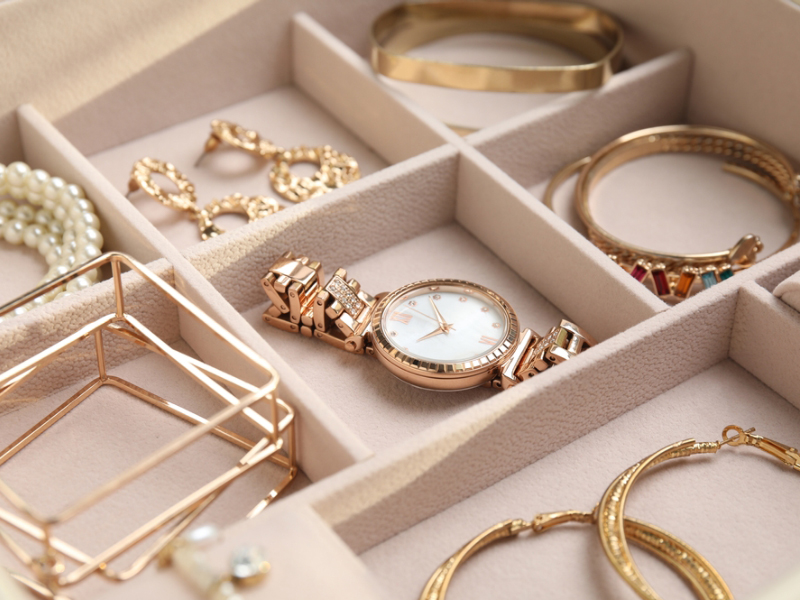
While your jewellery can be covered as part of your home insurance policy, a comprehensive jewellery insurance policy can offer additional coverage for various situations. These include:
- Accidental damage
- Loss
- Theft
- Loss or damage while travelling
- Loss of market value (if a covered piece of jewellery has been damaged and loses value, you will be compensated for any loss in its agreed value)
- Market appreciation
- Mysterious disappearance (for example, petty theft that you didn’t notice and therefore didn’t report straight away)
- Newly purchased pieces that have not yet been listed under your policy (usually up to 90 days)
Need some help with your Singapore insurance?
Contact the insurance specialists at Pacific Prime Singapore for questions about international health, dental, maternity and home insurance in Singapore and more.
Pacific Prime Singapore
18 Cross Street, China Square Central, #09-02
6346 3781 | pacificprime.sg
Read on for more about insurance and other health and fitness topics in Singapore.
Don't miss out on the latest events, news and
competitions by signing up to our newsletter!
"*" indicates required fields