Buying property in London as an investment or for your child’s studies
We catch up with JORDAN EDWARDS, owner of the Edwards & Plumb property company, to discuss how the company helps Singapore-based buyers navigate the London property market. From purchasing buy-to-let investments to finding the perfect apartments in London for children studying at university there, Jordan shares insights into the buying process, the challenges overseas buyers may face, and how his property company supports clients every step of the way — including ongoing property management for those looking to rent out their investments.
Jordan, tell us about your company and what you do.
I lived in Singapore for many years and have worked in property for 16 years, so I understand the challenges of buying property in London from overseas. I set up Edwards & Plumb in 2020 to help international buyers, and today most of our clients are based in Singapore. We’re a buyer’s agent, which means we work for the buyer, not the seller. We help clients find the right property, guide them through the purchase and provide someone they can trust on the ground in London. Whether it’s managing the buying process or looking after the property afterwards, we’re their eyes and ears locally, giving them peace of mind that everything is being taken care of, even when they’re thousands of miles away.
Most people you work with are buying property in London for one of two reasons. How do they differ?
Some clients want an investment, and others are parents buying somewhere for their son or daughter to live while studying in London.
For investors, it’s all about realistic returns, tenant demand and running costs. For parents, it’s more personal. Is the area safe? How long is the commute to campus? Will it still suit us after graduation, either to keep and let out or to sell? For a three-year degree, buying can make sense, but it depends on the budget, the area and how long you plan to hold the property. We talk this through at the start and explain the options for their budget, so they’re buying with a clear purpose.
Many London apartments sold in Singapore are off-plan or new-build. What’s your view?
These properties are often marketed to investors with rental returns that can be overly optimistic. For example, we manage a new-build apartment for a client who was promised a 6% yield but is actually achieving around 4% after running costs. Understandably, he’s disappointed.
That’s why we’re upfront about realistic rental returns, market conditions and ongoing costs before clients commit to a purchase. We’d rather they know the true figures from the start than be surprised or disappointed once they have purchased.
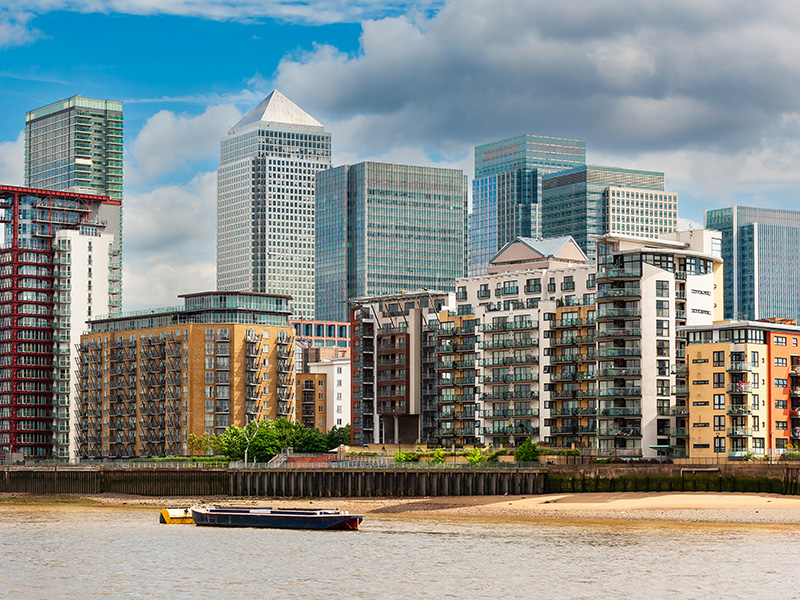
We also look beyond new-build developments, helping clients explore the wider London market, including resale properties and off-market opportunities that aren’t publicly advertised. For those buying to let, we can also manage the property, providing trusted support on the ground in London.
How are you different from a local estate agent?
Local estate agents work for the seller and are paid a percentage of the sale price, so they want the highest price. We work for the buyer. We look for value, negotiate the price and, if a property needs renovation or modernisation, explain what it will cost and factor that into the negotiation. Our fees are explained upfront.
What should buyers consider when considering new build vs an existing property in London?
Buying a brand-new apartment in a large development usually means fewer immediate repairs or maintenance costs, but you’ll still have ongoing service charges, which are also important to understand and consider.
An older or existing property may still have service charges to consider and understand, but you might need to set money aside for repairs or upgrades as the property ages.
It’s not just about the purchase price or rental yield. You also need to think about cash flow, ongoing costs and how much money you have readily available if unexpected expenses arise. We help clients weigh up these differences so they understand the full cost of owning the property before buying.
Are the online property portals a good place to search?
They’re useful for getting a feel for prices and areas, but for international buyers they’re often frustrating. Enquiries often go unanswered, some properties are already sold, and photos don’t always reflect the true condition of a property, particularly with enhanced or AI-edited images. There’s also the issue of agents keeping your details and contacting you about properties that don’t match what you’re looking for. And some of the best opportunities never make it onto the portals at all.
We shortlist suitable properties, arrange viewings and provide honest feedback on what they’re really like. We can handle video walk-throughs and negotiations remotely – some of our clients have been known to fly over and view shortlisted properties with me before making a final offer.
What should Singapore-based buyers know about UK costs and tax?
Buying overseas comes with more costs than the purchase price. Just as Singapore charges additional stamp duty to foreign buyers, the UK applies a stamp duty surcharge for non-UK residents, and it adds a meaningful amount to the cost of buying. Getting a mortgage as an overseas buyer is very doable, but you need the right broker because not every lender or broker works with non-residents.
That’s why we work with tax advisers, solicitors and mortgage brokers we trust. Our clients know all the numbers upfront, get the best arrangement available, and have support throughout the buying process and while they own the property.
What are the most common mistakes?
- Trusting inflated yields. It’s easy to get carried away by attractive rental returns, particularly when buying off-plan or new-build properties. It’s important to understand what you’ll actually earn, not just what’s being promised.
- Not researching the location properly. Just because a property is in London doesn’t automatically make it a good investment. Transport links, tenant demand, the condition of the building and future resale potential all matter.
- Not budgeting for all the costs. Taxes, legal fees, updating costs and management fees all affect returns, and so does the GBP/SGD exchange rate.
- Underestimating the time it takes. A one-week trip to London rarely finds the right property; it often takes weeks or months to find the right one at the right price. You also need time to get through legal conveyancing – unlike Singapore, in the UK this often takes months not weeks.
Can you give us a recent example?
We recently helped a family buy a one-bedroom flat in Central London for their son, who is studying here. We negotiated a price around 13% below the asking price. He’s now settled in and living there happily. I check in regularly with both the parents and their son to make sure everything is running smoothly and to help with anything they need.
How can people get in touch?
If you’re considering buying property in London, whether for investment or for your child’s studies, we’re happy to talk it through. Book a call with us via WhatsApp on +44 7485 548638, email jordan@
Want to feature your company in our print magazine or on expatliving.sg or social media? Email us at [email protected]!
Don't miss out on the latest events, news and
competitions by signing up to our newsletter!
"*" indicates required fields